ERIC Ask ERIC
Educational modelling only. ERIC explains CMP model output from your entered settings. Not financial advice, a suitability assessment or a personal recommendation.

Welcome to

CalculateMyPension

The pension planning website

Calculate My Pension was built because retirement planning has become unnecessarily difficult for ordinary people. Many free calculators are too basic to be useful, while full financial planning software is often aimed at advisers rather than individuals.

Where are you on the journey?

Calculate My Pension is designed to bridge that gap. It combines a detailed retirement cashflow model with clear explanations, so you can see not only the result, but also understand the assumptions behind it.

Our goal is to help people understand retirement planning better: how State Pension fits in, how tax affects income, how inflation changes spending power, and how withdrawals from pensions and savings may need to be managed over time.

We cannot give financial advice, but we can help you become better informed before making some of the biggest financial decisions of your life.

Every stage

The retirement planning journey

Calculate My Pension helps you at every stage of your journey, from early saving through to calculating sustainable withdrawals. If you're just starting out, the Free calculator is all you need. If you're approaching retirement or already retired, you will find the Premium calculator of great value.

Stage 1

More than a decade away

With retirement a long way off, there is time for any additional saving you make now to have a significant impact on your future retirement outcome. Save just a bit more each month and you could end up retiring years earlier.

The Free calculator helps you check if you are on track to retire at your target age and shows how many more years of retirement you could get by saving just a bit more.

Free

Stage 2

Approaching retirement

With retirement on the horizon, you will soon have some important decisions to make.

The Premium calculator shows the impact of each option on your retirement plans, reducing the need for costly financial advice. It can help you optimise your plans, allowing you to retire earlier and with confidence.

You can even Plan As A Couple.

Stage 3

Already retired

With your pension already in payment, your main concern will be knowing how much you can spend each year without your funds running out. Tax efficiency is a key concern to maximise long term withdrawals.

The Premium calculator provides the peace of mind that comes with knowing how much you can sustainably withdraw and that you are not paying any unnecessary tax.

A retired man at his kitchen table with paperwork and a calculator

Income needs

Assessing retirement income needs

Calculating what income you can afford in retirement is just one half of the retirement planning equation. The other half is understanding how much income you'll need to support your desired lifestyle.

We use the widely recognised Retirement Living Standards to help you estimate your personal income needs. These set out three standards of living, each with an income requirement that reflects real-world costs based on independent research.

MinimumModerateComfortable

The Retirement Budget Calculator allows you to tailor your retirement income needs in line with your own circumstances or preferences, using the same expense categories as the Retirement Living Standards research.

This provides a quick and easy way to allow for your own circumstances and preferences without already having a budget, while still using the Retirement Living Standards as a foundation. This tailored income target feeds directly into a comparison with your calculated affordable income, so you can see if you are on target and adjust your plans accordingly.

Couples

Plan as a couple

Retirement income needs are different for couples than for individuals. Two people living together can share many costs, such as housing, utilities and food. It therefore makes sense to plan for retirement as a couple rather than as two separate individuals. The Retirement Living Standards website helpfully provides target incomes for couples as well as individuals.

To work out when you can afford your chosen combined income target, our Plan As A Couple feature models both of your retirement plans together, assuming that you retire at the same time. Your two affordable incomes are added together and compared with your combined target income at different retirement ages, to find the earliest point at which you can afford to retire together.

You can also explore possible improvements in tax efficiency by redirecting contributions to your partner, or vice versa, depending on who has the higher marginal tax rate, and see how much this could improve your affordable retirement age.

A couple on a sofa looking at a tablet together
A balance scale weighing coins labelled Pension and ISA

Pension and ISA

Tax optimisation

Getting the balance right between drawing from your pension and your ISA could end up saving many thousands in tax over your whole retirement.

Calculate My Pension guides you through targeting the right level of pension withdrawal to make the most of your allowances, and provides the tools to optimise tax over your whole retirement. The model automatically uses your full tax-free Personal Allowance each year and the 25% tax-free element available through UFPLS withdrawals.

You can clearly see the amount of pension fund you need to withdraw each year to achieve this primary level of tax optimisation, avoiding unnecessary tax.

The next level is to find the best mix of withdrawals from your pension and ISA over and above the primary withdrawals to meet your required income. This depends on your circumstances and the projection assumptions being used. Experimenting with different pension and ISA income splits lets you find the mix that minimises your long-term tax bill.

You can also model the trade-off between pension and ISA contributions before retirement, weighing up giving up pension tax relief for greater flexibility and future tax-free withdrawals, and see the direct effect on your earliest affordable retirement age.

Risk

Stress testing

Three advanced modelling features let you investigate the impact of a market crash, along with measures to protect against it.

  • Market crash modelling

    Stress-test your plan by modelling a sudden fall in fund values at any age and for any percentage. See immediately whether a crash just before retirement would delay your plans, or how much spending would need to change if it happened after you had stopped working.

  • Asset mix modelling

    Set the proportion of your pension and ISA held in cash and short-term bonds and see the trade-off between stability and long-term growth. A more defensive allocation may reduce the impact of market falls in the short term, while a higher growth allocation can increase your affordable retirement income. The model rebalances each year and allows different strategies for each partner when planning as a couple.

  • Annuity purchase modelling

    Explore converting part of your pension into a guaranteed income for life at different ages and for different amounts. Compare the security of an annuity with the flexibility of drawdown, and see how guaranteed income can protect your long-term spending against poor investment returns or living longer than expected. An integrated calibration tool keeps the annuity rates used in line with current market conditions.

A woman at her desk in front of screens showing market charts
Tax free cash

Lump sums

Tax-free cash modelling

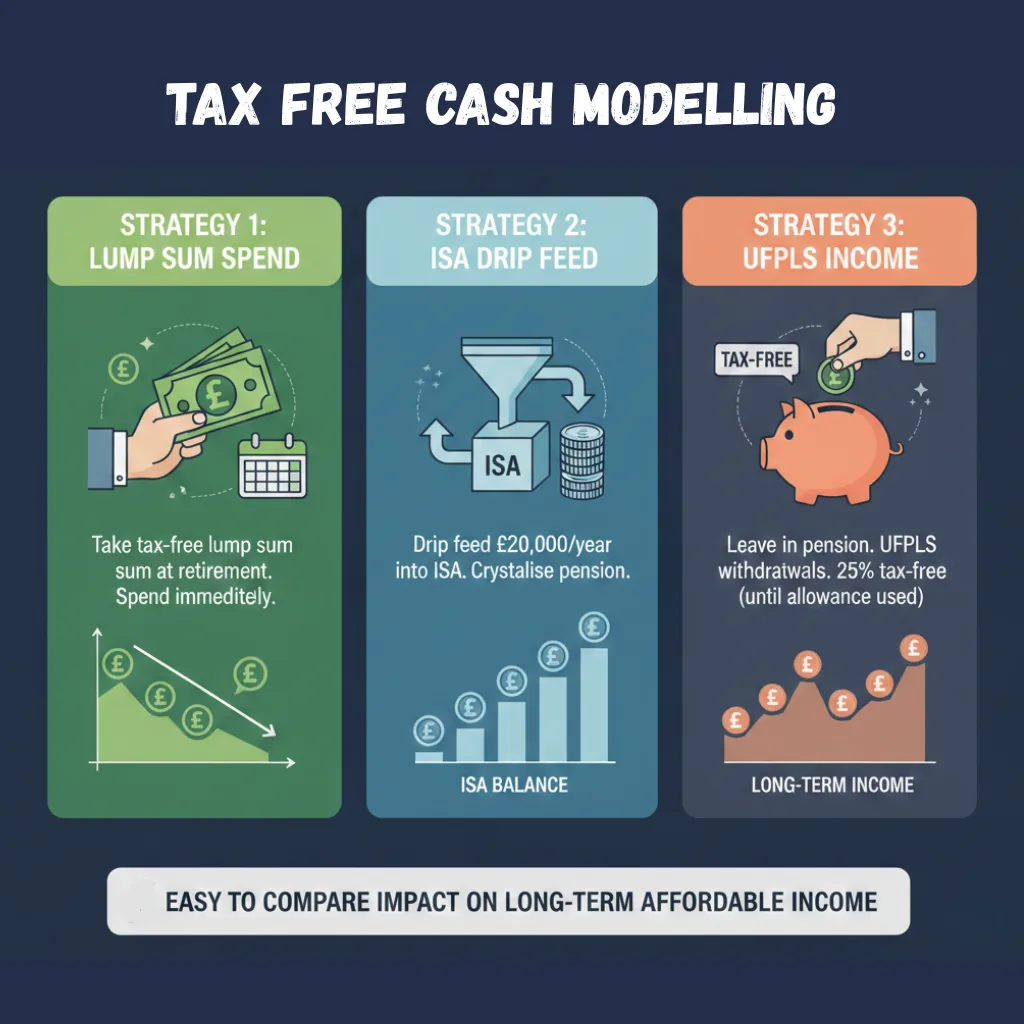
Your tax-free cash is one of the most valuable features of your pension, but the way you use it can make a significant difference to your retirement income over time. Calculate My Pension lets you test three clear strategies.

  1. 01Take your tax-free lump sum at retirement and spend it immediately.
  2. 02Drip feed £20,000 of it into your ISA each year.
  3. 03Use UFPLS, where 25% of each withdrawal is tax-free until your Lump Sum Allowance is used up.

It is easy to compare the impact of each strategy on your long-term affordable income. Pension income is assumed to be taken first from any uncrystallised funds that remain, so UFPLS is used by default.

Defined benefit

Taking your defined benefit pension early

If you are a member of a defined benefit pension scheme that allows you to take reduced benefits before the scheme's normal pension age (NPA), you can use the Defined Benefit Early Retirement Calculator to try taking your benefits at different ages, up to 12 years before your scheme's NPA.

Taking your benefits early may help to keep your gross income below certain tax thresholds and so increase your affordable income. It can also help to bridge the gap before your State Pension starts, giving you a base of guaranteed income early in retirement.

The calculator provides illustrative, conservative estimates of early retirement benefits based on standard factors and a single set of scheme rules. They are an approximate guide only (not quotes) but still very useful for retirement planning.

Deferred members

No longer building up benefits. Conservative sets of reduction factors are used to calculate your reduced pension and lump sum.

Active members

Still building up benefits. A few extra inputs allow for the fact that your projected benefits assume you continue to work and build up benefits until the scheme's NPA.

Defined benefit early retirement
NHS worker reviewing her pension on a laptop at home

NHS Pension Scheme

Free

NHS pensions

If you work for the NHS, your pension is probably one of the most valuable things you own. It is also one of the most complicated. The NHS Pension Scheme has three parts, and many people have pension in more than one of them, each with its own rules.

  • 1995 Section

    Full pension fromAge 60
    Builds up1/80thof final pay for each year
    Tax-free lump sumPaid automatically
  • 2008 Section

    Full pension fromAge 65
    Builds up1/60thof final pay for each year
    Tax-free lump sumBy exchanging some pension
  • 2015 Scheme

    Full pension fromState Pension age
    Builds up1/54thof each year's pay (career average)
    Tax-free lump sumBy exchanging some pension

Calculate My Pension models each part separately. Just enter the pension for each part from your Annual Benefit Statement. Each part starts at its own retirement age, with its tax-free lump sum included, and it is all built into the earliest age you can afford to retire. You can add your NHS pension in the two-minute setup, and it is free.

Don't have your statement to hand? The free NHS Pension Calculator works out your pension from your dates and pay, and shows McCloud Option A and Option B side by side.

Premium members can also use the NHS Early Retirement calculator, which applies the scheme's early retirement reduction factors, to see how taking each part earlier changes their affordable income or retirement age. Planning as a couple with two NHS pensions is also included.

Calculate My Pension is independent and is not affiliated with or endorsed by the NHS or NHS Pensions. Figures are illustrations, not quotations.
Plans

Free

Free features

The free features provide a valuable tool to all users. Open any feature to see what it does.

Your retirement age

4 features
When Can I Afford To Retire?
  • Get straight to the most important figure - the age at which you can afford to retire.
  • Based on your current provisions, your target income in retirement and a set of standard assumptions.
  • A smart search algorithm finds the age at which your affordable retirement income matches the inflation adjusted target income for your selected standard of living in retirement.
See The Effect of Saving More
  • Increase your planned pension contributions or ISA deposits and immediately see the impact on your affordable retirement age.
  • Seeing the impact of increased contributions in terms of additional months or years of enjoying your retirement can be a powerful motivator to save more.
See The True Cost Of Fund Charges
  • See the effect of different levels of charges on your affordable retirement age.
  • Choose from Low, Medium and High levels of charges or set the precise value for your pension fund and ISA using the sliders.
  • Select the Fund Charges chart in the Select Chart dropdown to see how your pension fund and ISA charges progress over time.
  • The effect on your affordable retirement age can be surprisingly large, even from what look like small percentage differences in annual charges.
Retirement Living Standards Comparison
  • See your affordable retirement age for each of the three recognised living standards: Minimum, Moderate, and Comfortable.
  • Use the Retirement Budget Calculator to personalise category-level spending and feed that target into your plan.
  • These standards are based on reliable, independent research from PensionsUK and are detailed on the official Retirement Living Standards website.

Pensions and income

3 features
Multiple Income Sources
  • The affordable retirement age calculation allows for your pension fund, ISA, any defined benefit pension you have, any other income you may have from part-time work or rent, and your State Pension.
  • These income sources may begin or end at different ages. This is all taken into account in the projections.
State Pension Projection
  • Your State Pension age is calculated automatically, along with the projected value of a full State Pension.
  • Use the UK government forecast service at gov.uk to get your personal forecast and input that amount to override the full State Pension assumption.
  • Allowing for your State Pension reduces the need to draw income from your pension fund, once it has commenced payment. Prior to that you are reliant on your pension fund and ISAs to bridge the gap.
NHS Pensions
  • Enter the pension shown on your NHS Annual Benefit Statement for the 1995 Section, 2008 Section and 2015 Scheme, along with your pensionable pay.
  • Each part is projected to retirement under its own rules and paid from its own normal pension age, or from your retirement if that is later, with the automatic 1995 Section lump sum included.
  • Choose how much pension to exchange for a tax-free lump sum in each part. The Lump Sum Allowance is applied automatically.
  • Affected by the McCloud remedy? Enter your Option A and Option B figures in turn to compare the results.
  • Use the free NHS Pension Calculator to work out the pension built up in each part from your dates and pay, and compare McCloud Option A and Option B side by side.

Tax

2 features
Accurate Tax Calculations
  • Tax on withdrawals from your pension fund is accurately calculated assuming current income tax rules continue and allowing for all other types of retirement income.
  • Tax bands are frozen until 2031 and this is allowed for in the projections. Bands are assumed to rise with inflation after that point.
  • There is also an option to use the Scottish income tax rules if you are a Scottish taxpayer.
Tax Optimisation
  • Your pension fund withdrawal plan automatically fully utilises your tax-free personal allowance to maximise tax-free withdrawals early on in retirement.
  • It also allows for 25% tax-free withdrawals under the UFPLS (Uncrystallised Funds Pension Lump Sum) arrangement by default.
  • Funds from your ISA are used to top up your income to the target level until your ISA funds run out, helping keep your retirement income tax-free for as long as possible.

Charts and tables

3 features
Income Breakdown Chart
  • View a clear breakdown of your net retirement income in each future year by source, including pensions, ISA withdrawals, State Pension, and other income.
  • See the chart as projected future values or with all values in today's money terms.
  • Choose between monthly or annual amounts.
  • Hover the cursor over an entry to see the actual figures behind the breakdown.
Projected Fund Values Chart
  • See how your pension fund and ISA are project to grow with investment return and contributions until retirement and then decrease as you withdraw funds in retirement, ending up at zero at the end of the projection.
  • See your retirement age plotted on the pension fund line.
Cashflow Tables

Access the detailed numerical breakdown behind your charts with clear and concise tables:

  • Retirement Income: View exact gross and net income from each source.
  • Pension Fund and ISA Cashflow: Review projected opening and closing balances each year and clearly see all cash movements in and out.

Tools and help

3 features
Useful Calculators

Access helpful supplementary calculators:

  • Tax Calculator: Clearly understand your tax and National Insurance contributions. View detailed breakdowns by tax bands, including specific calculations for the Scottish tax regime.
  • Salary Sacrifice Calculator: Instantly see how different salary sacrifice levels affect your take-home pay and pension contributions. Also quantify the effect of the future cap on your take-home pay.
  • NHS Pension Calculator: Work out your NHS pension from your dates and pay, with McCloud Option A and Option B shown side by side.
  • Standalone Inheritance Tax Calculator: Estimate inheritance tax due, net estate value, and potential shortfall versus accessible assets on a dedicated calculator page.
FAQs Page
  • Quickly find clear and concise answers to the most common questions on retirement planning, grouped intuitively by category.
  • An ideal resource to build your knowledge and confidence around pensions and retirement.
Securely Save Your Inputs
  • Sign up for free to set up an account and log in at a later date and resume your investigation with the same inputs from where you left off.
  • There is a button to clear all inputs and start again if required.
  • The inputs are stored securely and are not shared with any third parties.

Plans

Premium

Premium features

Premium adds the modelling you need as retirement gets closer, on top of everything in Free.

£79.99 a year

Retirement Planning

4 features
Plan As A Couple
  • Plan for retirement as a couple by modelling both of your pensions together and recognising the shared cost advantages of living under one roof.
  • Uses the official couple's cost of living benchmarks from the Retirement Living Standards (Minimum, Moderate and Comfortable standards of living).
  • See the exact age (years and months) at which you can afford to retire together, based on your chosen combined retirement income target.
  • Explore smarter contribution strategies by redirecting pension savings between you and your partner to reduce tax drag where one of you pays a higher marginal rate.
  • Instantly quantify how improved joint tax efficiency could move your retirement date forward — and understand the real-world impact on when you can stop working together.
Download Retirement Guide PDF
  • Download a retirement guide, bringing together the key inputs, assumptions and projected outcomes in one place.
  • Use it as a practical reference when reviewing scenarios, comparing options, or preparing for a conversation with Pension Wise or a regulated financial adviser.
Carry Forward Calculator
  • See how much you can pay into your pension this tax year using unused annual allowance from the last three tax years, with the taper and the Money Purchase Annual Allowance built in.
  • Works for employees, the self-employed and company directors: shows the most you can pay in personally and the most your employer or company can pay in.
  • Shows the tax relief and net cost of a planned personal contribution, any annual allowance charge, and the allowance you lose if it isn't used by 5 April.
  • Save the result to your plan and use it as a one-off pension contribution with one switch.
One Off Pension Contributions
  • Add a single pension contribution in the first year of your plan – for example part of a bonus, or profits your own limited company pays in for you.
  • Enter it gross or net: tax relief is added to personal contributions, and company or employer contributions go in gross.
  • See straight away how it changes your affordable retirement age and income, for you or your partner.

Defined Benefit Pension Options

3 features
Defined Benefit Lump Sum
  • Model a defined benefit lump sum paid by your scheme alongside the annual pension.
  • CMP applies your remaining Lump Sum Allowance, treats any excess as taxable pension income, and shows the impact in the year the lump sum is paid.
  • Where the tax-free part is available for reinvestment, the projection can reflect how it supports ISA funding and later cashflow.
Additional Defined Benefit Pensions
  • Add extra defined benefit pensions where you have more than one scheme, while keeping your largest or most important scheme in the main DB section.
  • Set the annual pension amount, start age and indexation treatment for each additional scheme.
  • Each pension is included in the retirement income breakdown and taxed alongside State Pension, drawdown and other income.
Defined Benefit Early Retirement
  • Experiment with taking a reduced defined benefit pension before the scheme's normal pension age.
  • Enter scheme-specific early retirement factors where available, so CMP can estimate the annual pension and tax-free lump sum payable at the selected age.
  • See how starting guaranteed income earlier changes pension withdrawals, tax, fund balances and the income needed from other sources.

NHS Pension Options

4 features
NHS Early Retirement
  • Choose the age you claim your 1995 or 2008 Section benefits and your 2015 Scheme benefits, from the scheme's minimum pension age up to 75.
  • The scheme's published early retirement reduction factors are applied to the pension and lump sum, with late retirement increases where 2008 and 2015 benefits are taken later while you are still in NHS employment.
  • See how claiming each part earlier or later changes your affordable income or retirement age, your tax and the income needed from your other savings.
Working On In The NHS
  • Treat part-time earnings after retirement as continuing NHS pay, so your 2015 Scheme pension keeps building up and your 1995 or 2008 Section benefits keep their link to pay until you stop.
  • Late retirement increases apply while you are still working in the NHS.
NHS Pensions For Couples
  • Model both partners' NHS pensions, each with their own parts, lump sum choices and claim ages.
  • See the age at which you can afford to retire together, with both NHS pensions in the plan.
Your NHS Pension In The Retirement Guide
  • The downloadable Retirement Guide shows each part of your NHS pension, and each lump sum, at the age it is paid.
  • A dedicated page explains your own NHS pension and your options, and the projection timeline marks when each part starts.

Tax Modelling Options

6 features
Tax Free Cash Modelling

Your tax-free cash is one of the most valuable features of your pension, but the way you use it can make a significant difference to your retirement income over time.

Calculate My Pension lets you test three clear strategies:

  • Take your tax-free lump sum at retirement and spend it immediately.
  • Drip feed £20,000 of it into your ISA each year.
  • Use UFPLS, where 25% of each withdrawal is tax-free until your Lump Sum Allowance is used up.

It is easy to compare the impact of each strategy on your long term affordable income. You can also combine two of the three strategies for a hybrid approach.

PCLS vs UFPLS
  • Compare PCLS, Phased Drawdown and UFPLS: take tax-free cash at retirement, release it gradually, or take withdrawals where 25% of each eligible payment is tax free.
  • See how each approach changes taxable pension income, ISA balances, remaining pension funds and the timing of Lump Sum Allowance usage.
  • Model the trade-off between receiving tax-free cash early and spreading tax-free pension withdrawals across retirement.
Pension vs ISA Contributions
  • Test the impact of redirecting contributions from your pension into your ISA, or vice versa.
  • Instantly see the impact of this on your earliest retirement age. The extent of the effect very much depends on your individual circumstances, along with the economic scenario you are using.
  • Understand the value of pension tax relief you are giving up in exchange for greater financial flexibility.
Tax Band Optimisation
  • Model how pension and ISA money are drawn in retirement, so you can compare withdrawal strategies and the effect on lifetime tax.
  • Fill your Personal Allowance from pension withdrawals first, and optionally extend this to the basic-rate band where paying some 20% tax now may avoid higher-rate tax later.
  • See the trade-off directly in the Income Breakdown and Tax by Tax Band charts, including how State Pension and defined benefit income reduce the room available for tax-free pension withdrawals.
Tax Charts

Access to three additional charts relating to tax payments:

  • Tax By Tax Band: See the breakdown of your tax payments in each retirement year split by tax band. This makes it easy to see how you might adjust your plans to reduce overall tax payments.
  • Tax Free Allowance: See the cumulative tax free allowance as up to 25% of your pension income is tax free but only up to a lifetime maximum of £268,275. When this limit is reached you will see a significant increase in tax, so it is worth considering adjustments to your drawdown plan to avoid this.
  • Marginal Tax Rate: See your projected marginal income tax rate over time, based on the tax due on the next £100 of gross income in each year. This helps you identify when extra taxable income is likely to be taxed at a higher rate.
Inheritance Tax Projection
  • Project inheritance tax liability over time directly on the Analysis page, alongside your pension and ISA projections.
  • See when estimated inheritance tax exceeds accessible assets, highlighting potential pressure on the family home.
  • Test planning options such as minimum ISA balance targets and assumptions around pension use after age 75 to manage inheritance tax outcomes.

Illustrative Stress Scenarios

4 features
Investigate Market Crash Scenario
  • Stress-test your retirement plans by simulating a market crash.
  • Choose the age at which the crash occurs and the percentage fall.
  • See the impact on your retirement age of a sudden market crash just before you were planning to retire.
  • Or if you are already retired, see the impact of your sustainable income if a crash were to occur. How much would you need to reduce your spending by?
Experiment with a Cash Buffer
  • Set a cash buffer as a fixed amount and/or a percentage of your funds
  • Set the expected interest rate on your cash balances
  • Use alongside the market crash scenario to see the level of protection
  • Quatify the trade off between reduced investment risk and lower long term returns
Investigate Annuity Purchases
  • Annuities provide a guaranteed income for life, removing the stress of volatile fund values and the risk of poor long term fund growth. They also insure you against living longer than were expecting to.
  • They are back in fashion as annuity rates have increased dramatically over the last few years, driven by the rise in interest rates.
  • With this premium feature you can investigate purchasing an annuity for different amounts at different ages and see the impact on your sustainable retirement income.
  • To ensure the rates used by the calculation reflect your circumstances and the latest market rates, an Annuity Rate Calibration Tool is also provided to align the conversion rates to the level that are currently available.
Model Changes to Government Policy

See the effect of possible changes to government policy on your retirement age or income:

  • State Pension Age: See the effect on your earliest affordable retirement age if the state pension age is raised to 70.
  • Tax Band Freeze: Tax bands are currently frozen until 2031. See the effect of a possible extension to this freeze on your retirement age. You can specify the number of extra years to freeze the bands.
  • Tax Free Lump Sum Limits: See the impact on your retirement plans of a reduction of the 25% tax free lump sum maximum. Also see what would happen if the lifetime limit on tax free cash of £268,275 is reduced.

Withdrawal Strategy

5 features
Income Boost
  • Plan a temporary uplift in spending for a set period of retirement.
  • Particularly useful when planning as a couple to cover any early shortfalls your partner has, or vice versa.
  • Choose the Age To Commence Boost, the Percentage Boost, and the Number of Years.
One-Off Expenses
  • Add any number of one-off retirement costs, such as a car, wedding, major holiday or home repairs, as fixed pound amounts.
  • Specify each expense by age, calendar year or number of years from now. Use Today's Money to increase a current estimate to the payment year using the plan's inflation assumption.
  • The cost increases the cash required in that retirement year and follows the normal withdrawal and tax calculation. Expenses dated before the calculated retirement age are ignored.
Income Step-Down
  • One very effective way to boost your early retirement spending, or retire earlier, is to plan ahead for lower income needs in your later retirement years.
  • It is often the case that people slow down their activity once past their mid-70s. Your required spending may decrease. Specifically planning for this allows you to maximise activity in those early years.
  • With this premium feature you can specify the age at which and by what percentage your income will reduce, in two separate steps, and instantly see how this strategy impacts your retirement income or allows an earlier retirement.
Minimum ISA Balance
  • Set a minimum ISA balance cushion to keep in place throughout retirement.
  • Specify your Minimum ISA Balance (£) to preserve flexibility for later years or unexpected costs.
  • See how maintaining this floor impacts your sustainable income and retirement timing.
Defer Your State Pension
  • Model the effect of deferring your State Pension beyond your State Pension age.
  • See how a higher later State Pension compares with the extra income needed from pensions, ISAs or other savings during the deferral period.
  • When planning as a couple, test deferral separately for each person so the timing of guaranteed income reflects each partner's own State Pension age.

Other Income & Balances

5 features
Part Time Earnings
  • Add part-time earnings during retirement and choose the age at which they stop.
  • The income is included in the retirement income breakdown and taxed alongside pension withdrawals.
  • When planning as a couple, the same modelling can be applied separately for your partner.
Rental Income
  • Model monthly rental income after allowable expenses, with tax applied in the same way as other earned income.
  • Add the rental property value, age at sale, and allowable deductions on sale to estimate capital gains tax.
  • At sale, the net property proceeds are added to the GIA balance and shown in the GIA cashflow and fund value projections.
GIA Balance
  • Add a current General Investment Account balance and track it separately in the GIA cashflow table.
  • Choose whether to drip-feed £20,000 per year into your ISA and set a constant tax drag assumption for GIA growth.
  • GIA withdrawals are prioritised before ISA withdrawals once the plan needs ISA-style income, with the remaining balance included in fund charts and inheritance tax projections.
Gilt Ladder / Misc Lump Sums
  • Add planned lump sums at specific ages, such as maturing gilts, fixed-term savings, bond ladders, bonuses or other one-off receipts.
  • Enter each amount separately and specify its timing by age, calendar year or number of years from now.
  • The amounts are added into the GIA cashflow, helping you see how known future cash receipts could support withdrawals, reduce pressure on pensions or ISAs, and affect later balances.
Future Inheritance Lump Sums
  • Add any number of expected inheritances and specify when each is received by age, calendar year or number of years from now.
  • Enter the amount expected on receipt, or use Today's Money and set an individual annual growth rate to project a current estimate forward.
  • Each resulting inheritance enters that person's GIA in the selected year, then follows the normal GIA growth, ISA transfer and withdrawal rules. Your partner can maintain a separate list.

Premium includes all of these features for £79.99 per year. The subscription renews automatically each year until cancelled. Promotional codes can be entered at checkout.